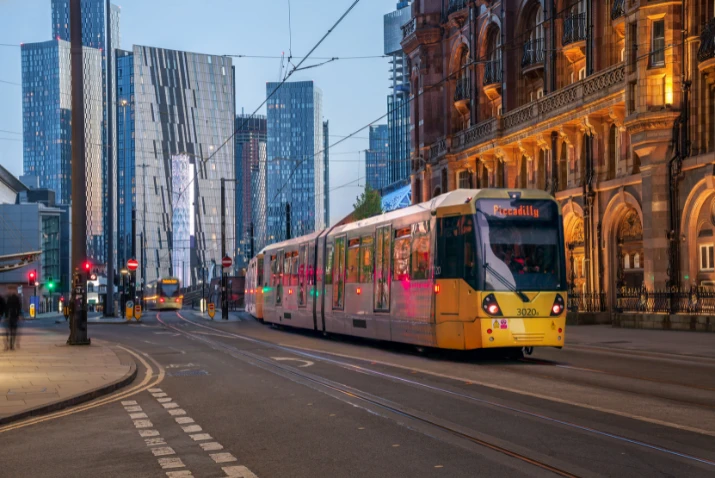
Manchester is one of the UK’s best-known regional cities and has long been shaped by growth, reinvention and investment. From its industrial heritage to its modern role as a major employment, education, healthcare, cultural and transport centre, the city continues to attract people who want to live, work and study there.
For property investors, Manchester’s appeal is easy to understand. It has a large and growing population, a substantial private rented sector, major universities, strong employment anchors and significant regeneration programmes. The latest evidence shows that Manchester’s population reached 589,670 in 2024, up 8.01% over five years, while Census 2021 recorded almost one-third of households in the private rented sector.
However, this does not mean every investment will work. Manchester is a large, varied market. City-centre flats, student HMOs, suburban family homes and regeneration-led areas can all perform differently. Investors need to understand the relationship between prices, rents, demand, supply, regulation and local neighbourhoods before buying.
The city also has an important affordability challenge with the Housing Needs Assessment identifying just under 40,000 households in need. This matters because strong demand can support rental markets, but stretched affordability can also limit what tenants and buyers can pay.
5 key considerations before investing in Manchester property
There are several key points anyone looking to invest in residential property in Manchester needs to understand before making a decision.
1. Prices and rents
According to the latest Office for National Statistics data, the provisional average house price in Manchester was £251,000 in June 2026. This was up 2.9% from June 2025, but still below the UK average of £272,000. It was above the North West average of £220,000.
Average prices by property type in Manchester in June 2026 were:
• Detached properties: £478,000
• Semi-detached properties: £328,000
• Terraced properties: £253,000
• Flats and maisonettes: £195,000
This price spread is important. Manchester has seen a lot of flat-led development, especially in and around the city centre, but houses and flats can behave very differently price wise. The ONS data shows that, in the year to June 2026, average terraced house prices in Manchester rose by 4.4%, while flats hardly increased at all +1.1%.
Rents in Manchester
The average monthly private rent in Manchester was £1,365 in July 2026, up from £1,316 in July 2025. That is a 3.8% annual rise. The North West average was £965, while the UK average was £1,393.
This shows Manchester rents are well above the regional average, although still slightly below the UK average. For investors, this is encouraging from an income perspective, but it is important to remember that average rent figures can hide big differences by property type, location and tenant group.
Average rents by number of bedrooms in Manchester in July 2026 were:
• One bedroom: £998
• Two bedrooms: £1,227
• Three bedrooms: £1,425
• Four or more bedrooms: £2,005
By property type, average rents were:
• Flats and maisonettes: £1,142
• Terraced properties: £1,397
• Semi-detached properties: £1,487
• Detached properties: £1,867
What is worth noting from a buy-to-let perspective is that larger homes do command higher rents, but they also cost more to buy and can involve higher running costs. The investment case depends on the purchase price, the likely tenant profile and management costs and comparing the extra cost of delivering a shared house versus a single one.
Source: ONS housing prices in Manchester
2. Will demand continue to increase?
When considering an area for investment, it is important to look at demand before looking at the property itself. Investors need to understand population growth, employment, housing supply and specialist demand, such as students and sharers. Without this, you are effectively buying a property and keeping your fingers crossed.
Manchester’s population was 589,670 in 2024, an increase of 8.01% from 2019 to 2024. This was higher than the North West’s 5.08% growth over the same period. Census data also shows Manchester’s population rose from 503,100 in 2011 to 552,000 in 2021, a 9.7% increase, compared with 5.2% across the North West and 6.6% across England.
The city also has a young, working-age population. In 2024, Manchester’s median age was 30, and 70.84% of residents were aged 16 to 64, compared with 62.57% across the North West. This is important for investors because younger and working-age residents are more likely to need private rented accommodation, flats, shared housing and homes close to jobs and transport.
Manchester’s Housing Needs Assessment also models population growth from 562,100 in 2022 to 623,500 in 2039, an increase of 61,400 people. This is plan-led evidence rather than a guaranteed forecast, but it does suggest the city is planning for continued growth.
Overall, there is strong evidence of demand, but investors still need to be careful. Demand in Manchester is not the same everywhere. City-centre renters, student households, young professionals, families and benefit-supported tenants all have different affordability levels and property needs.
Sources: ONS local indicators for Manchester
3. Does Manchester have a strong economy?
Manchester’s economy is strong and appears to be outperforming many other UK cities. According to Public Sector Executive, citing the latest Big Cities Outlook from Centre for Cities, job growth in Manchester has risen by 19.7% over the past decade, compared with a UK average of 13.9%. The city is also reported to have around 244,000 knowledge-intensive business services jobs, second only to London among UK cities, with particular strength in sectors such as digital, fintech and research.
This helps reinforce Manchester’s role as a major employment centre, which is important for property investors because a strong jobs market can support demand from young professionals, graduates and higher-skilled workers.
The city also has strong institutional demand anchors. Manchester University NHS Foundation Trust employs more than 28,000 staff and operates a major hospital and clinical-service estate across Manchester and Trafford. The city’s universities are also a major part of the housing story, with the University of Manchester and Manchester Metropolitan University supporting a large student and graduate population.
From a rental perspective, this matters because strong employment and education anchors help support demand from:
• Young professionals
• Students
• Graduates
• Healthcare workers
• University and education staff
• Commuters and city-centre workers
• Internationally mobile households
However, strong employment does not automatically mean every property will deliver a good return. Investors still need to consider local salaries, affordability, property condition, service charges, mortgage costs, licensing, void periods and tenant demand at neighbourhood level.
4. What is happening with housing supply?
Manchester has a significant housing requirement. The city’s plan-led housing requirement is 60,061 net dwellings between 2022 and 2039, equivalent to an annual average of 3,533 homes.
Recent completions have increased, but delivery has still been below the cumulative requirement:
• 1,891 completions in 2022/23
• 2,962 completions in 2023/24
• 3,138 completions in 2024/25
This left a three-year undersupply of 2,608 dwellings at 1 April 2025.
At the same time, Manchester City Council reported 32,670 deliverable dwellings for the period from 1 April 2025 to 31 March 2030, equivalent to a 7.5-year housing land supply. This means there is a substantial identified pipeline, but identified supply is not the same as completed homes.
Another important point is the type of homes being delivered. Manchester’s 2025 Authority Monitoring Report records that 84% of net residential completions in 2024/25 were flats, with the city centre accounting for almost two-thirds of net completions.
This is important for investors because it shows that new supply is heavily concentrated in flats and the city centre. That may suit some renters, but it will not meet every housing need, nor an investor’s objectives.
James Taylor, senior branch manager at Leaders Manchester, says, “Having worked in our Manchester city centre for the past eight years, I’ve seen the residential property landscape change significantly, with multiple high-rise apartment developments transforming the city centre forever and increasing the supply of modern rental accommodation. At the same time, we’ve seen letting demand continue to rise, reflecting Manchester’s growth and strong appeal to renters, which is continuing to support investor confidence in the city’s residential property market.”
5. Capital growth, yield and regulation
Manchester’s headline prices remain below the UK average, while rents are significantly above the North West average. On paper, this can make the city attractive to investors looking for income. However, the investment case needs to be assessed carefully by property type and area.
Property prices in Manchester have generally performed better than many areas in the North, with average values broadly keeping pace with inflation since 2005. However, investors need to look beyond the headline figures and check how different property types are performing. In many cities, house price growth is being driven mainly by houses, while flats in some locations may be worth little more than they were 10 years ago. Manchester’s flat market appears to have been less affected by this trend, but it is still important to compare flat and house price growth carefully before investing.
Megan Farnell, senior sales manager at Leaders, says, “Manchester remains one of the UK’s most exciting property investment markets, offering investors strong rental returns, a growing population and significant opportunities across both established and emerging neighbourhoods. For investors looking to build a diverse and resilient portfolio, great opportunity lies in identifying the right property in a good location and balancing reliable rental returns and long-term capital growth.”
HMOs and licensing
Manchester has a strong student and shared-rental market and investors need to be aware of the rules and always check whether licensing is required – even if you aren’t planning to do room shares.
Mandatory HMO licensing applies to qualifying privately rented HMOs with five or more occupants from two or more households sharing facilities. Manchester City Council states that it does not currently operate an additional HMO licensing scheme. Selective licensing applies in named areas including Cheetham, Clayton and Openshaw, Crumpsall, Gorton and Abbey Hey, Harpurhey, Levenshulme, Longsight, Moss Side, Miles Platting and Newton Heath, and Rusholme.
Manchester also has a citywide Article 4 Direction removing permitted development rights for changes from Class C3 homes to Class C4 HMOs. This means investors cannot simply assume they can convert a family house into a small HMO without planning considerations.
Source: Manchester City Council Article 4 Directions
Student demand in Manchester
Student demand is one of Manchester’s most important rental-market drivers, but it is highly localised.
Census 2021 recorded 7,796 students in Fallowfield, equal to 54.7% of its population. Ardwick had 9,411 students, representing 47.3% of its population. The University of Manchester’s Fallowfield Campus Redevelopment is also planned to provide up to 3,300 new bedspaces and increase beds by up to 950.
This supports the importance of areas such as Fallowfield, Ardwick, Rusholme and the wider university belt for shared housing and student accommodation. However, investors need to factor in HMO rules, local planning restrictions, licensing, management intensity and the potential impact of new purpose-built student accommodation.
Regeneration and future supply
Manchester’s regeneration story is a major part of its investment appeal. Key schemes include Victoria North, Holt Town and Wythenshawe.
Victoria North is identified as a major long-term housing growth area, with the North Manchester Strategy referring to 15,000 new homes across seven neighbourhoods, including 20% affordable homes. Holt Town is identified by Manchester City Council as having potential for up to 4,500 homes and 30,000 sq ft of workspace, while the wider Wythenshawe Civic masterplan provides for up to 2,000 homes over a 10 to 15-year period.
Regeneration can improve places, transport, amenities and long-term housing supply. However, investors should avoid assuming that regeneration automatically creates capital growth. Programme figures can change, and delivery depends on planning, funding, phasing and build-out.
Overall investment view for Manchester
Overall, Manchester has many of the ingredients investors look for: a growing population, a large private rented sector, strong employment anchors, major universities, high student demand, significant regeneration and a substantial housing pipeline.
The city’s average house price remains below the UK average, while rents are well above the North West average. This can make Manchester attractive, particularly for investors who understand the difference between city-centre flats, suburban houses, HMOs, student lets and regeneration-led locations.
However, Manchester is not a simple “buy anywhere” market. New supply is heavily flat-led, affordability is under pressure, HMO growth is controlled, and yields vary significantly by property type and location. Investors need to check the numbers carefully and make sure the property matches their objectives, whether that is income, capital growth, or a balance of both.
The key is to invest with proper local advice. Working with professionals such as Leaders Manchester and Leaders Fallowfield who understand Manchester’s neighbourhoods, licensing rules, tenant demand and property types can help investors identify the right opportunity for the short and long term.